All Categories
Featured
Table of Contents

Adopting Smart Financial Systems in Delaware
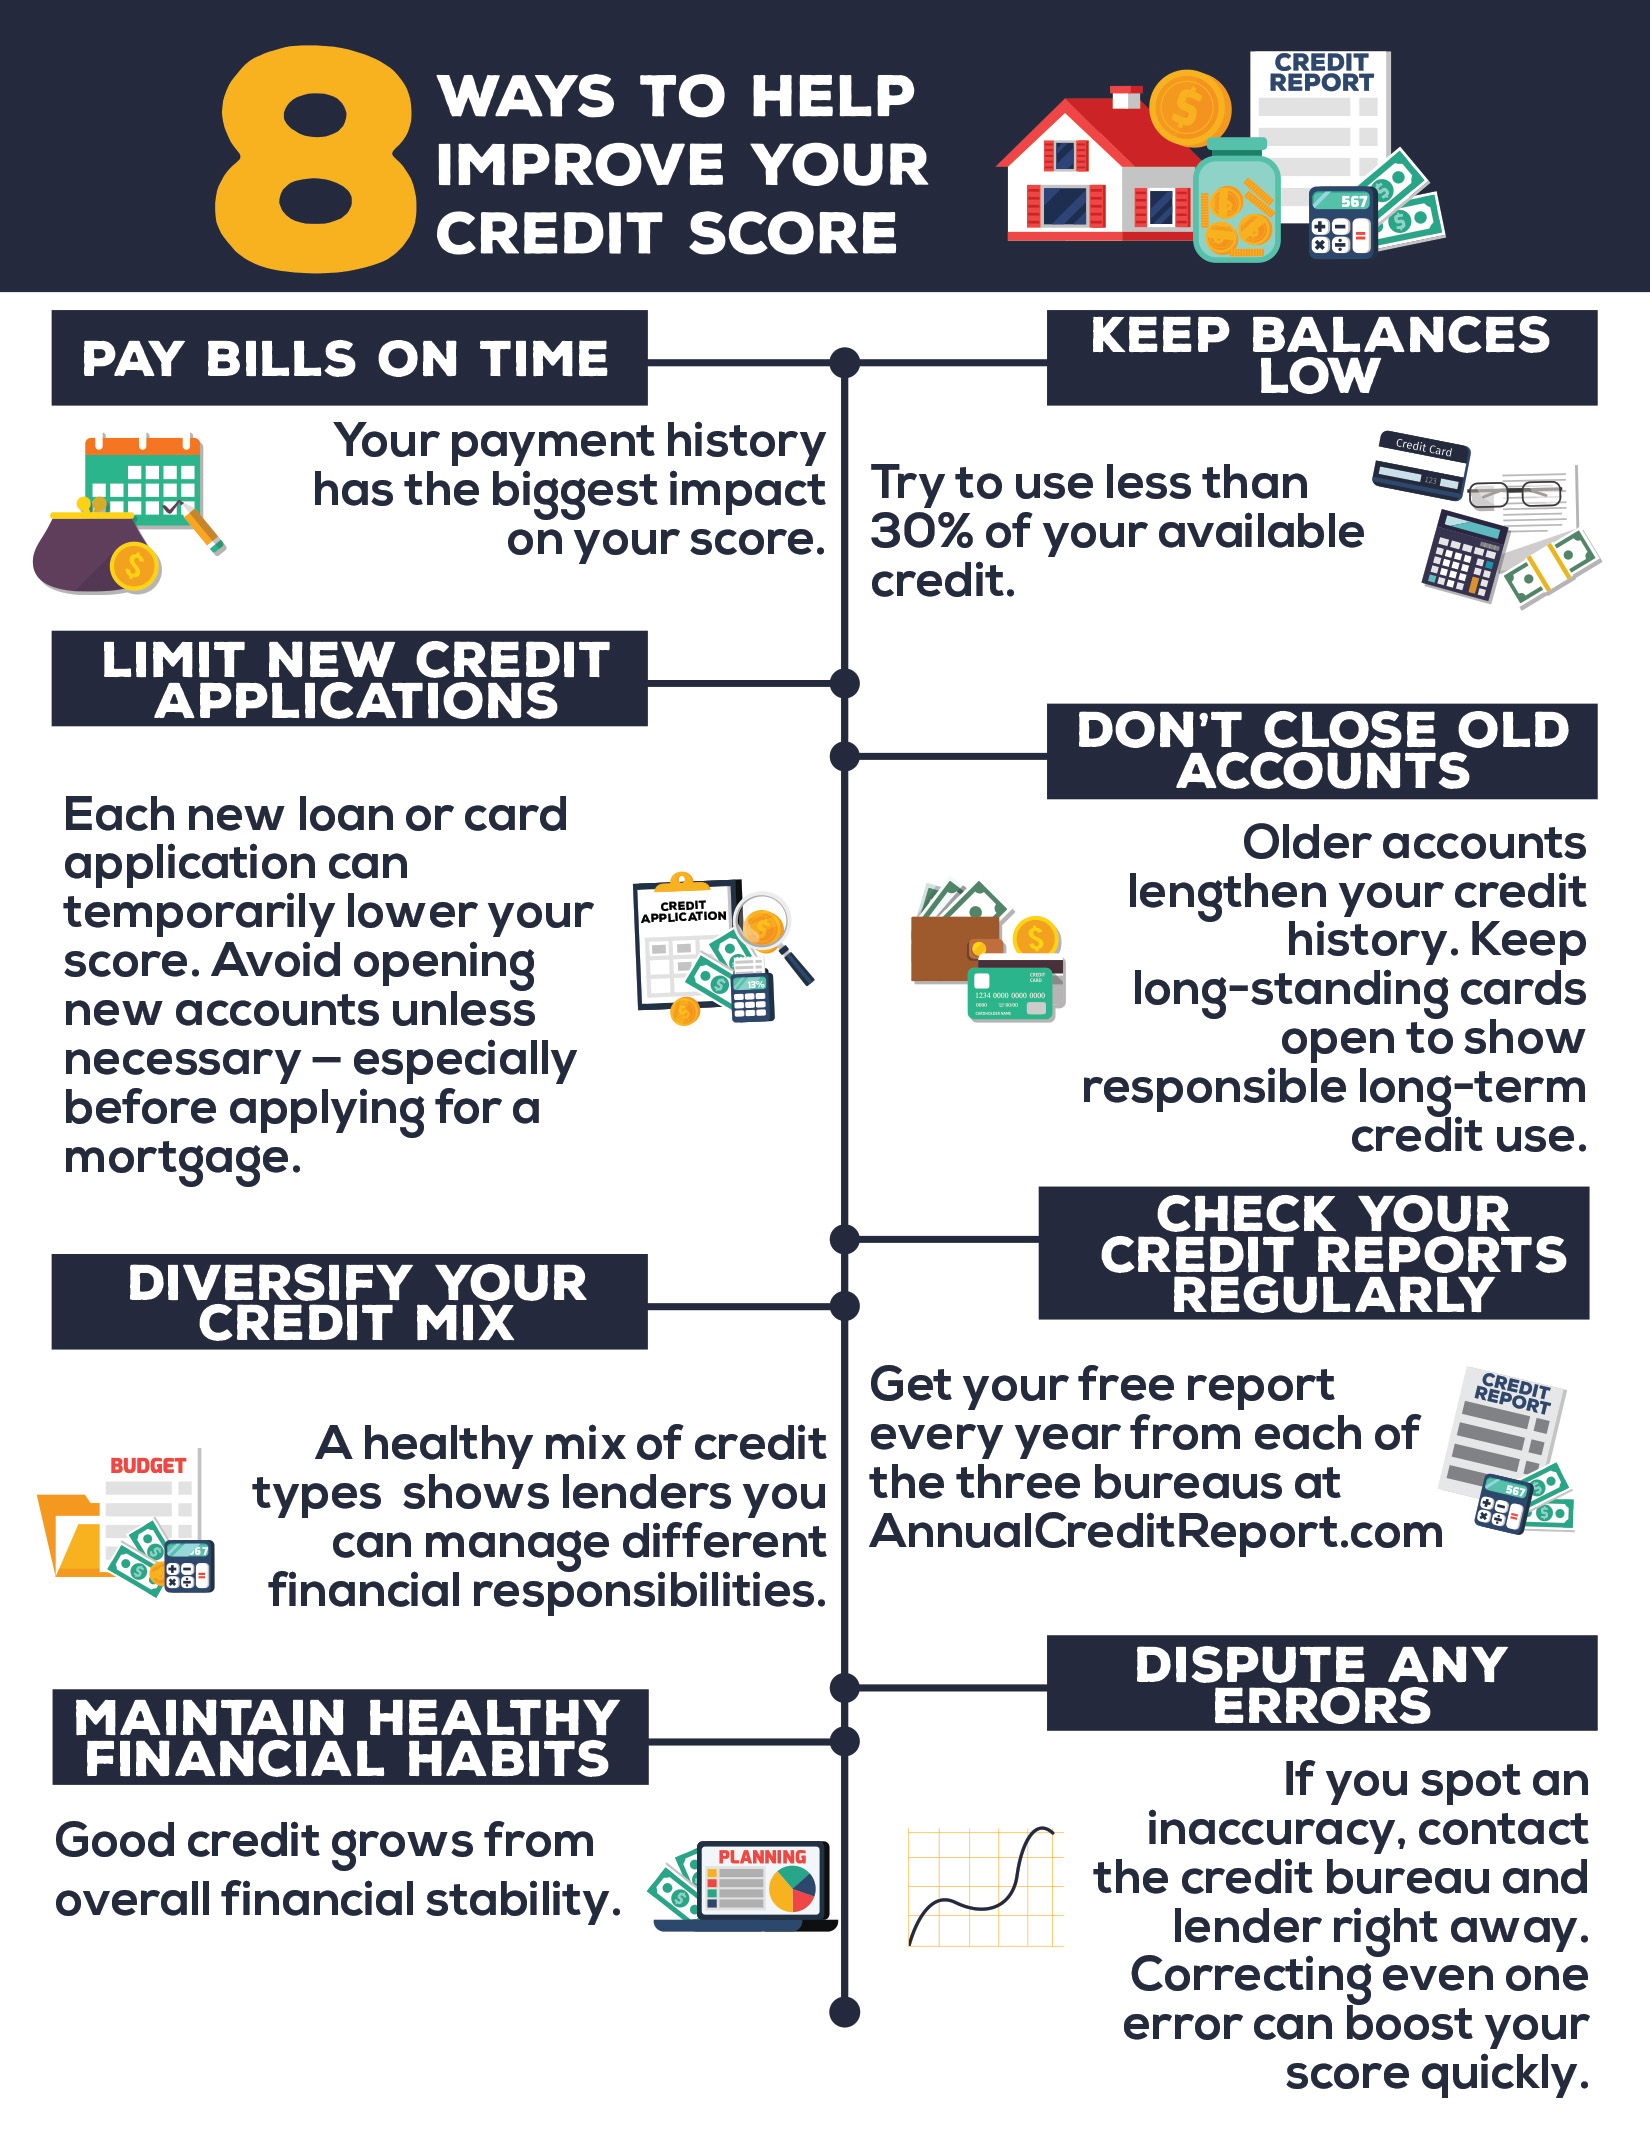
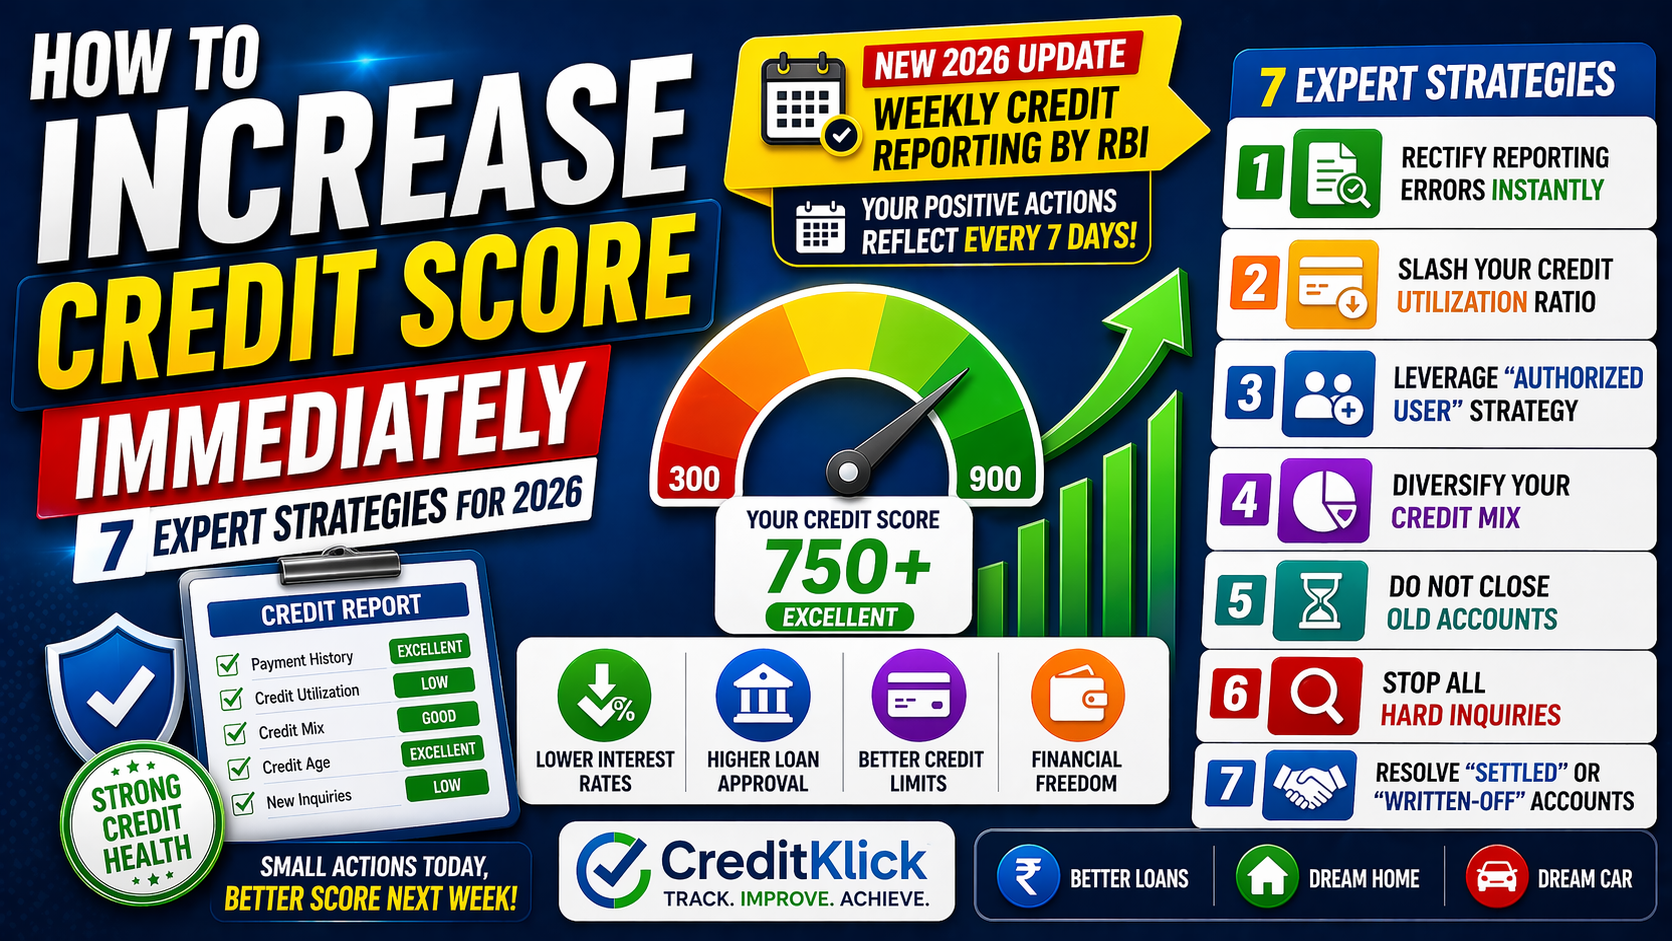
Financial management by 2026 has actually transitioned from manual record-keeping to extremely advanced, self-governing systems. The reliance on paper statements or manual calendar suggestions has largely faded as customers prioritize performance and accuracy. Developing a strong credit profile in 2026 needs more than just paying costs on time; it includes establishing a defensive architecture that prevents errors before they happen. Experts tracking trends in Delaware observe that homeowners who utilize automated oversight tend to maintain scores considerably higher than those who count on memory.The core of this strategy depends on the synchronization of bank accounts, charge card, and reporting companies. In the existing year of 2026, financial organizations supply innovative interfaces that permit granular control over payment timing and quantity. Rather of basic "set it and forget it" designs, modern automation utilizes predictive logic to make sure that payments are made when they most benefit the credit usage ratio. This shift is especially noticeable when taking a look at credit management programs, which now typically integrate straight with individual banking apps to provide real-time updates.Success in 2026 depends on Report Analysis to make sure that every financial action contributes positively to a credit report. This method reduces the danger of human error, which stays a leading reason for accidental rating drops. By removing the manual component, customers ensure that their credit rating reflects constant, responsible habits without the friction of monthly tasks.
Advanced Autopay Strategies for Delaware
Basic autopay was as soon as a blunt instrument that merely moved money on a specific date. In 2026, professional monetary therapists advise a tiered technique. The very first tier includes "Micro-Payments" or "Regular Cycling." Instead of one big payment at the end of the month, automated systems can be set to pay off small balances every time they reach a specific threshold. This keeps the reported balance low at all times, which is a significant consider the credit rating models utilized throughout 2026. Professional Wealth Building Strategies offers clear paths for improvement by ensuring that credit utilization stays listed below 10 percent. For lots of in Delaware, high cost-of-living expenditures can lead to high credit card balances if not managed daily. By automating multiple payments throughout the billing cycle, the reported utilization stays minimal, even if the total month-to-month costs is significant. This method is a staple of expert therapy techniques in 2026, enabling individuals to utilize their charge card for rewards without the charge of high balance reporting.Another layer of this technique includes "Buffer Automation." This is the practice of establishing secondary accounts that instantly cover any shortages in a primary monitoring account. In 2026, these sweeps are immediate, preventing "non-sufficient funds" errors that might lead to missed payments. This protective step is frequently discussed by professionals familiar with local credit enhancement firms as a method to protect a best payment history versus unanticipated bank hold-ups or timing mismatches.
Incorporating AI-Driven Alerts and Changes

The year 2026 has actually seen the increase of AI assistants that do more than simply notify a user of an expense. These assistants now evaluate costs patterns and anticipate when a credit rating may be at threat. If an automated subscription increases its rate suddenly, the system can flag it as a prospective danger to a specific budget goal. This level of oversight is necessary for those navigating the intricate monetary environment of Delaware. Monitoring services in 2026 have actually evolved to include "Artificial Scams Defense" and "Automated Conflict Filing." If an unauthorized account appears on a credit report, automated systems can start the very first actions of an obstacle before the user even logs in. This speed is essential because credit scoring designs in 2026 respond rapidly to new information. A delay of a few days in reporting an error can lead to a rating drop that takes months to recover.Increased interest in Wealth Building in 2026 has forced loan providers to be more transparent about how they report data. Borrowers who utilize automated tools to investigate their own reports find that they can catch disparities that manual evaluations frequently miss. These tools compare the information throughout all 3 major bureaus and highlight any disparities in payment history, account age, or credit line. In Delaware, where competitors for low-interest loans is high, having a clean and precise report is a requirement rather than a high-end.
Credit Mix and Automated Diversity
A healthy credit profile in 2026 requires a diverse mix of account types. While lots of people focus entirely on charge card, scoring designs also search for installation loans, such as automobile loans or personal loans. Therapists often suggest using automated "Credit Home builder Loans" for those who need to diversify their mix without handling high-interest financial obligation. These items instantly deduct a small quantity each month, hold it in a protected account, and report the on-time payments to the bureaus.In Delaware, these automated home builder tools are frequently coupled with credit consulting packages to supply a thorough strategy. The beauty of these systems is that they operate in the background. When the initial setup is complete, the customer can focus on their career or individual life while their credit rating gradually climbs up. This hands-off approach is the gold standard for financial health in 2026. Beyond installation loans, 2026 has introduced more methods to include non-traditional information in credit reports. Automation enables the reporting of rent, utility, and even streaming service payments. Solutions that specialize in this information aggregation make sure that every on-time payment for a cell phone expense or an apartment in Delaware counts towards the last rating. For more youthful borrowers or those new to the nation, this automated inclusion of "soft" credit information is a main way to develop a footprint.
Preserving Security in an Automated Environment
With increased automation comes the need for heightened security. In 2026, monetary therapy includes a heavy focus on digital health. This suggests using encrypted password managers and two-factor authentication for every account connected to an automatic system. Expert consultants in Delaware stress that while automation saves time, it does not remove the need for regular human audits.A common recommendation is the "Quarterly Sync-Up." Every three months, a customer should examine all automated triggers to ensure they still align with present income and goals. If a person receives a raise or changes tasks in 2026, their automated payment limits should be adjusted appropriately. This makes sure that the system continues to work for the individual's existing reality rather than their past circumstances.Data privacy likewise remains a concern. When using digital financial tools, it is vital to comprehend what information is being shared and with whom. The guidelines of 2026 provide more protection for customers, but the responsibility of picking reputable platforms stays with the user. Searching for services that have a strong track record of security within Delaware is a sensible step before connecting high-value accounts.
The Long-Term Effect of Financial Autonomy
The cumulative impact of these automated techniques is a more durable monetary standing. By 2026, the gap in between those who use innovation to handle their credit and those who do not has widened. The speed at which credit decisions are made-- typically in seconds by AI lenders-- indicates that there is no longer any margin for error. A single late payment in 2026 can be more harmful than it was a years earlier because the systems are more sensitive to current data.Moving towards a fully automated design permits homeowners of Delaware to move with more agility. Whether obtaining a mortgage or a business loan, having a credit report that is kept by an accurate, automatic system supplies a level of confidence that manual tracking can not match. The expert methods of 2026 highlight that credit is a tool to be managed with technical precision, not a mystery to be feared.As the year 2026 advances, the tools available for credit management will only become more integrated and intelligent. Accepting these changes is the most reliable way to ensure long-term financial health. By setting up a system that prioritizes low usage, consistent payments, and accurate reporting, anybody can accomplish a top-tier credit history. The shift toward automation represents a democratization of financial knowledge, putting the power of a professional counselor into the pocket of every consumer.

Latest Posts
Finding No-Cost Credit Assistance for Me in 2026
Building Credit Through Advanced Financial Literacy Education
A Guide to Improving Credit in 2026