All Categories
Featured
Table of Contents

Modern Approaches to Wealth in 2026
The year 2026 has brought a shift in how people view and manage their personal finances. Gone are the days when basic savings accounts and basic 401k contributions sufficed to protect a comfy future. The present financial environment needs a more technical understanding of how credit, debt, and properties connect. This is where expert financial counseling has stepped in to fill a gap that technology alone can not bridge. In 2026, the human component of counseling focuses on data analysis and behavioral psychology to help people navigate a market that feels more automatic than ever.
Financial counselors now serve as navigators through a complicated maze of digital possessions and standard liabilities. They highlight that wealth building is no longer a fixed goal however a constant procedure of modification. Lots of individuals in Massachusetts have actually found that generic suggestions from 2025 or earlier no longer applies. Rather, therapists are taking a look at real-time information to predict how rates of interest shifts and inflationary pressures will affect private acquiring power. Interest in Dating Health has actually increased as people look for ways to safeguard their properties from unpredictable market swings.
Advanced Credit Building Methods in Massachusetts
Credit has become the main tool for wealth generation in 2026. It is no longer just a step of one's capability to pay back a loan but a reflection of total monetary health. Expert therapists frequently start by auditing a person's digital credit profile. This includes looking beyond the 3 basic bureaus to see how alternative information, such as utility payments and membership histories, influences lending decisions. High-tier counseling approaches include "credit laddering," where consumers tactically open and manage particular types of accounts to trigger positive motions in their internal bank scores.
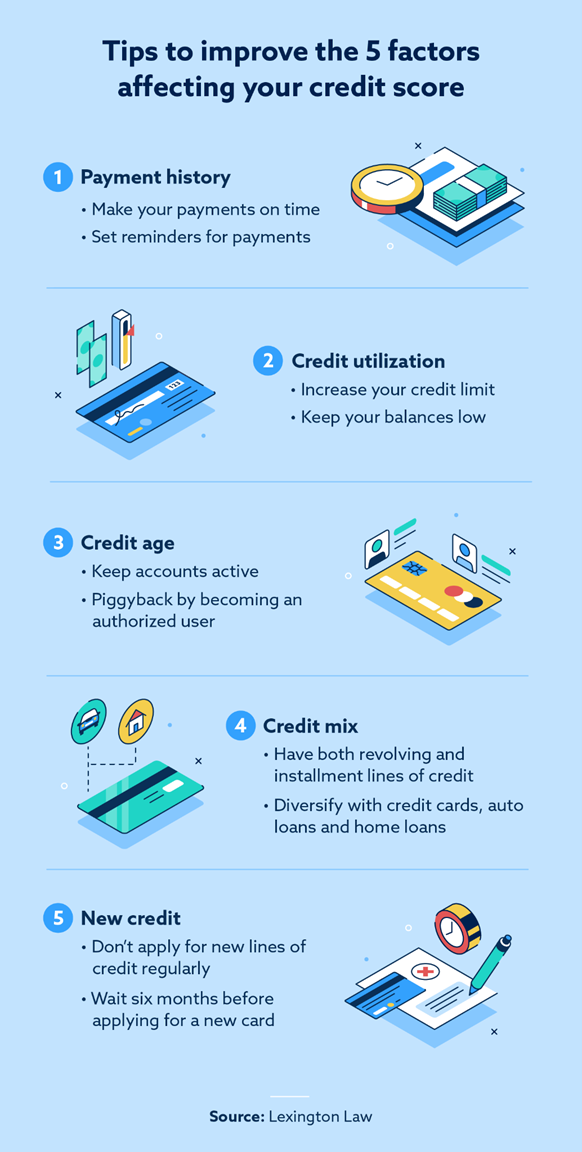
Effective credit management in the current year typically includes more than simply paying bills on time. It needs a deep understanding of usage ratios and the timing of reporting cycles. People seeking Debt frequently discover that the day a balance is paid matters as much as the quantity paid. By lining up payment dates with declaration closing dates, savvy consumers can synthetically decrease their reported debt, which can cause immediate score improvements. Financial Dating Health Standards uses a structured method to handle complex financial obligation circumstances that may otherwise stall a person's development towards homeownership or organization investment.
The Impact of Debt on Regional Growth
Economic stability in Massachusetts is closely connected to the credit reliability of its residents. When a large percentage of the population has access to low-interest capital, the entire local economy feels the advantage. Financial counselors are focusing heavily on "algorithmic hygiene," a practice that includes cleaning up digital footprints that may adversely affect a person's financial standing. This includes disputing mistakes in automatic reporting systems that have ended up being more common as AI-driven background checks become the standard for everything from home leasings to task applications.
Therapists also teach clients how to use credit as a bridge to investment. In 2026, it is typical to utilize low-interest credit lines to fund revenue-generating assets. This method needs discipline and a clear exit technique, both of which are main themes in modern counseling sessions. Success in modern-day markets often requires specialized Financial Software in 2026 to make sure that every financial move is backed by existing information instead of out-of-date presumptions.
Technological Integration in 2026 Wealth Counseling
While the human counselor remains main to the process, the tools they use have actually altered. In 2026, monetary therapy includes the usage of predictive modeling to show customers precisely where they will remain in five or 10 years based on their current habits. These designs take into account cost-of-living adjustments specific to Massachusetts. This level of information assists remove the uncertainty from budgeting and enables more aggressive wealth-building strategies. A counselor may suggest moving funds from a traditional cost savings account into a high-yield digital bond or a fractional real estate platform, depending upon the customer's danger tolerance.
Psychology also plays a larger role in these sessions. Counselors are trained to determine "investing triggers" that are frequently intensified by the 2026 digital shopping environment. With one-click purchases and social media-driven intake at an all-time high, the therapist's task is to offer a buffer between the impulse and the action. They assist clients develop strong monetary routines that can endure the continuous pressure to invest. This behavioral coaching is frequently the difference between someone who just manages and somebody who in fact constructs a significant net worth in time.
Building Resiliency Through Debt
Financial resiliency is the capability to recuperate quickly from obstacles. In 2026, problems can be available in the type of unexpected task shifts or unanticipated medical expenses. Therapists recommend an "emergency situation credit technique" together with traditional emergency situation funds. This involves preserving high-limit, zero-balance credit cards that can be utilized in a crisis, ensuring that the person does not need to liquidate long-term financial investments at a loss. This dual-layered approach to security supplies peace of mind and allows for more confident long-lasting preparation.
The objective of counseling in Massachusetts is to move the client from a state of monetary defense to a state of financial offense. This indicates being proactive about debt rather than reactive. Instead of awaiting a costs to become an issue, therapists help clients restructure their financial obligation before it affects their score. This may include combining high-interest loans into a single, manageable payment or negotiating with lenders for better terms based upon a long-standing history of reliability. These techniques prevail in expert circles however typically overlooked by the public.
The Future of Wealth in Massachusetts
Looking towards the end of 2026, the demand for high-level financial guidance is anticipated to increase. As the space between those who comprehend the digital economy and those who do not continues to broaden, the role of the therapist ends up being a lot more substantial. They are the gatekeepers of financial literacy, offering the tools necessary for the typical individual to contend in a market dominated by institutional players. By focusing on credit structure and tactical financial obligation management, these experts are helping to produce a more equitable monetary environment.
Wealth building in 2026 is less about picking the ideal stock and more about preserving the right monetary profile. A high credit report and a low debt-to-income ratio are the secrets to accessing the very best chances. Whether somebody is looking to purchase their first home in Massachusetts or beginning a small company, the structure is always the very same. Professional counseling provides the plan, the accountability, and the technical knowledge to turn those objectives into a truth. The focus stays on consistent, sustainable development that can weather the inescapable shifts of the coming years.
By treating credit as a primary asset, people can open levels of wealth that were formerly booked for the upper class. The democratization of financial tools has made this possible, however it is the guidance of a professional that makes it practical. As 2026 advances, those who welcome these contemporary counseling approaches will likely find themselves in a much stronger position than those who hold on to the financial routines of the past. Success refers preparation, information, and the willingness to adjust to an altering economic environment.

Latest Posts
Finding No-Cost Credit Assistance for Me in 2026
Building Credit Through Advanced Financial Literacy Education
A Guide to Improving Credit in 2026