All Categories
Featured
Table of Contents
Shifting Truths of Credit Assessment in Delaware
The financial environment of 2026 has moved far from the fixed, regular monthly pictures that defined the previous decade. For citizens in Delaware, the method credit reliability is measured now depends on a continuous stream of information points instead of a single number upgraded every thirty days. Modern algorithms have actually moved toward cash-flow underwriting, which focuses on actual liquidity and spending routines over historical financial obligation management alone. This change implies that a person's everyday financial habits brings more weight than it did just a couple of years back.
Financial counselors in 2026 emphasize that the conventional credit history is ending up being a secondary metric. Lenders are progressively utilizing exclusive designs that integrate directly with checking account to verify earnings and outbound expenses in real-time. This shift has actually been driven by the need for more precise danger assessment in an economy where gig work and non-traditional income streams are typical. For those residing in Delaware, these changes offer both chances and difficulties, as a single month of poor money management can reflect on a profile much faster than under older systems.
One noteworthy advancement in 2026 is the prevalent adoption of trended information. Rather of looking at a balance on a particular day, algorithms now analyze whether a customer is "paying down" or "revolving" their financial obligation over a 24-month duration. This difference assists lenders determine individuals who are caught in a cycle of debt versus those who are actively improving their monetary position. Lots of individuals discover that focusing on Income Budgeting assists keep a favorable trajectory even if their overall financial obligation remains moderate.
Combination of Alternative Data Points
By 2026, the inclusion of "alternative" data has become standard practice across all major bureaus. This consists of rent payments, energy costs, and even subscription services. Formerly, these items just appeared on a report if they went to collections, but modern models reward constant on-time payments for these daily expenses. This change has actually assisted countless people with "thin" credit files develop a footprint without requiring to take on high-interest charge card financial obligation.
In Delaware, local home management firms and energy companies have actually mainly automated the reporting of these payments. Therapists frequently advise clients to guarantee their preferred financial tool is properly connected to these accounts to optimize the advantage. If an individual pays lease on the first of the month for three years directly, the 2026 algorithms treat this as a high-intent sign of dependability, similar to a mortgage payment. This leveling of the field enables renters to compete for better rates of interest on auto loans and individual lines of credit.
Expert techniques now involve "information health" rather than simply balance management. Consumers are motivated to audit their digital monetary footprint to ensure that no small, forgotten subscriptions are triggering friction in their information stream. Since Modern Credit Goals Frameworks offers a clear window into financial routines, keeping a clean and foreseeable spending pattern is the most efficient method to develop a high rating in the current year.
The Effect of AI and Predictive Modeling
Device learning has essentially altered how threat is determined in 2026. Unlike older linear designs, AI-driven algorithms can identify complicated connections that people may miss. For instance, a sudden shift in where a person shops or a modification in the frequency of small-dollar transfers can set off a danger alert. These designs are not searching for a specific error, but rather a modification in the "financial speed" of the person. This predictive nature indicates that ratings can fluctuate based on perceived future danger, even if no payments have been missed out on.
This predictive modeling has led to the rise of individualized credit coaching. Counselors in Delaware usage software that mirrors these AI designs to offer customers a "pre-score" evaluation. This permits individuals to see how a particular purchase or a brand-new credit inquiry may impact them before they take action. In 2026, the objective is to get rid of the mystery of why a score moves. Most consumers now have access to "what-if" simulators that are even more precise than the generic tools available in the early 2020s.
For those aiming to enhance their standing, the focus has moved toward "positive signaling." This includes purposefully creating information points that the AI views as low-risk. Many individuals seeking Credit Freedom for Households find that preserving a high "buffer" in their monitoring account is simply as essential as keeping credit card balances low. The algorithm views a consistent money reserve as an indication that the consumer is unlikely to rely on high-interest financial obligation during an emergency.
New Credit Structure Methods for 2026
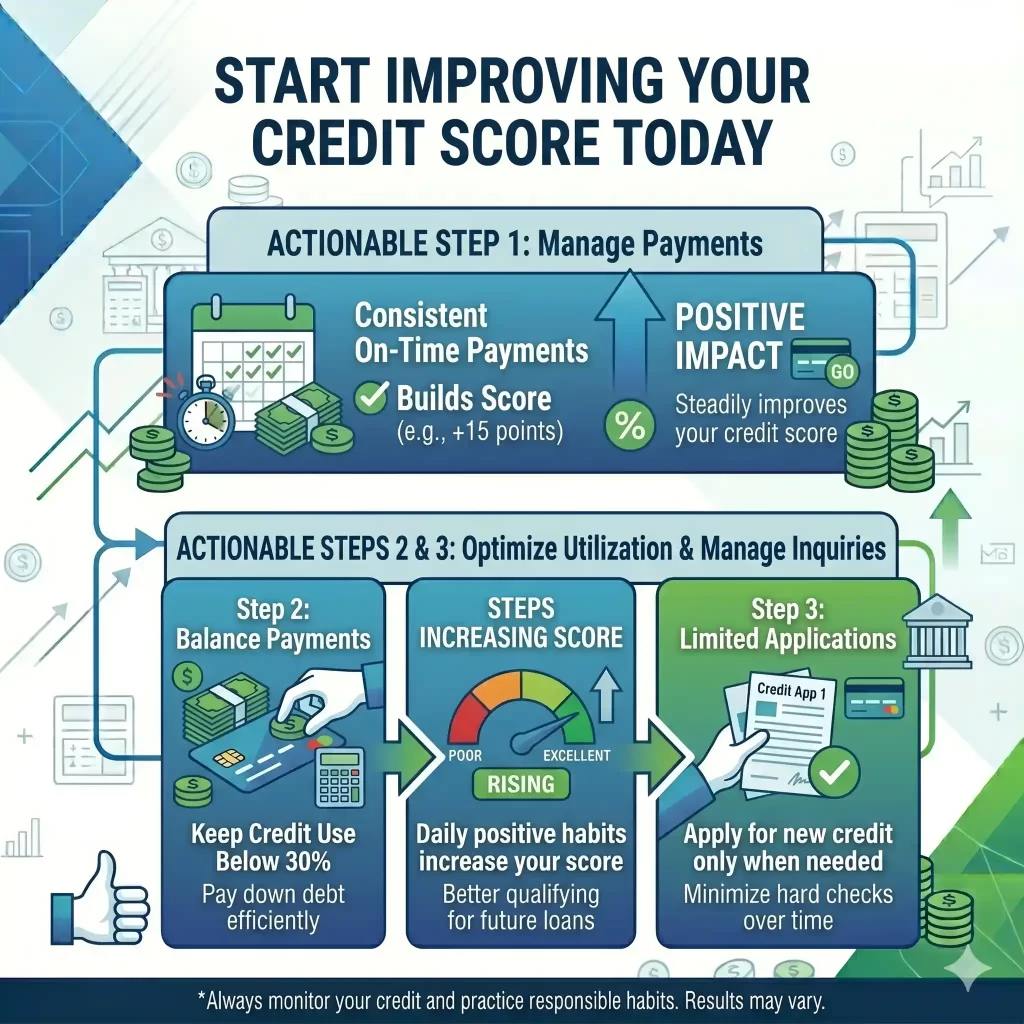
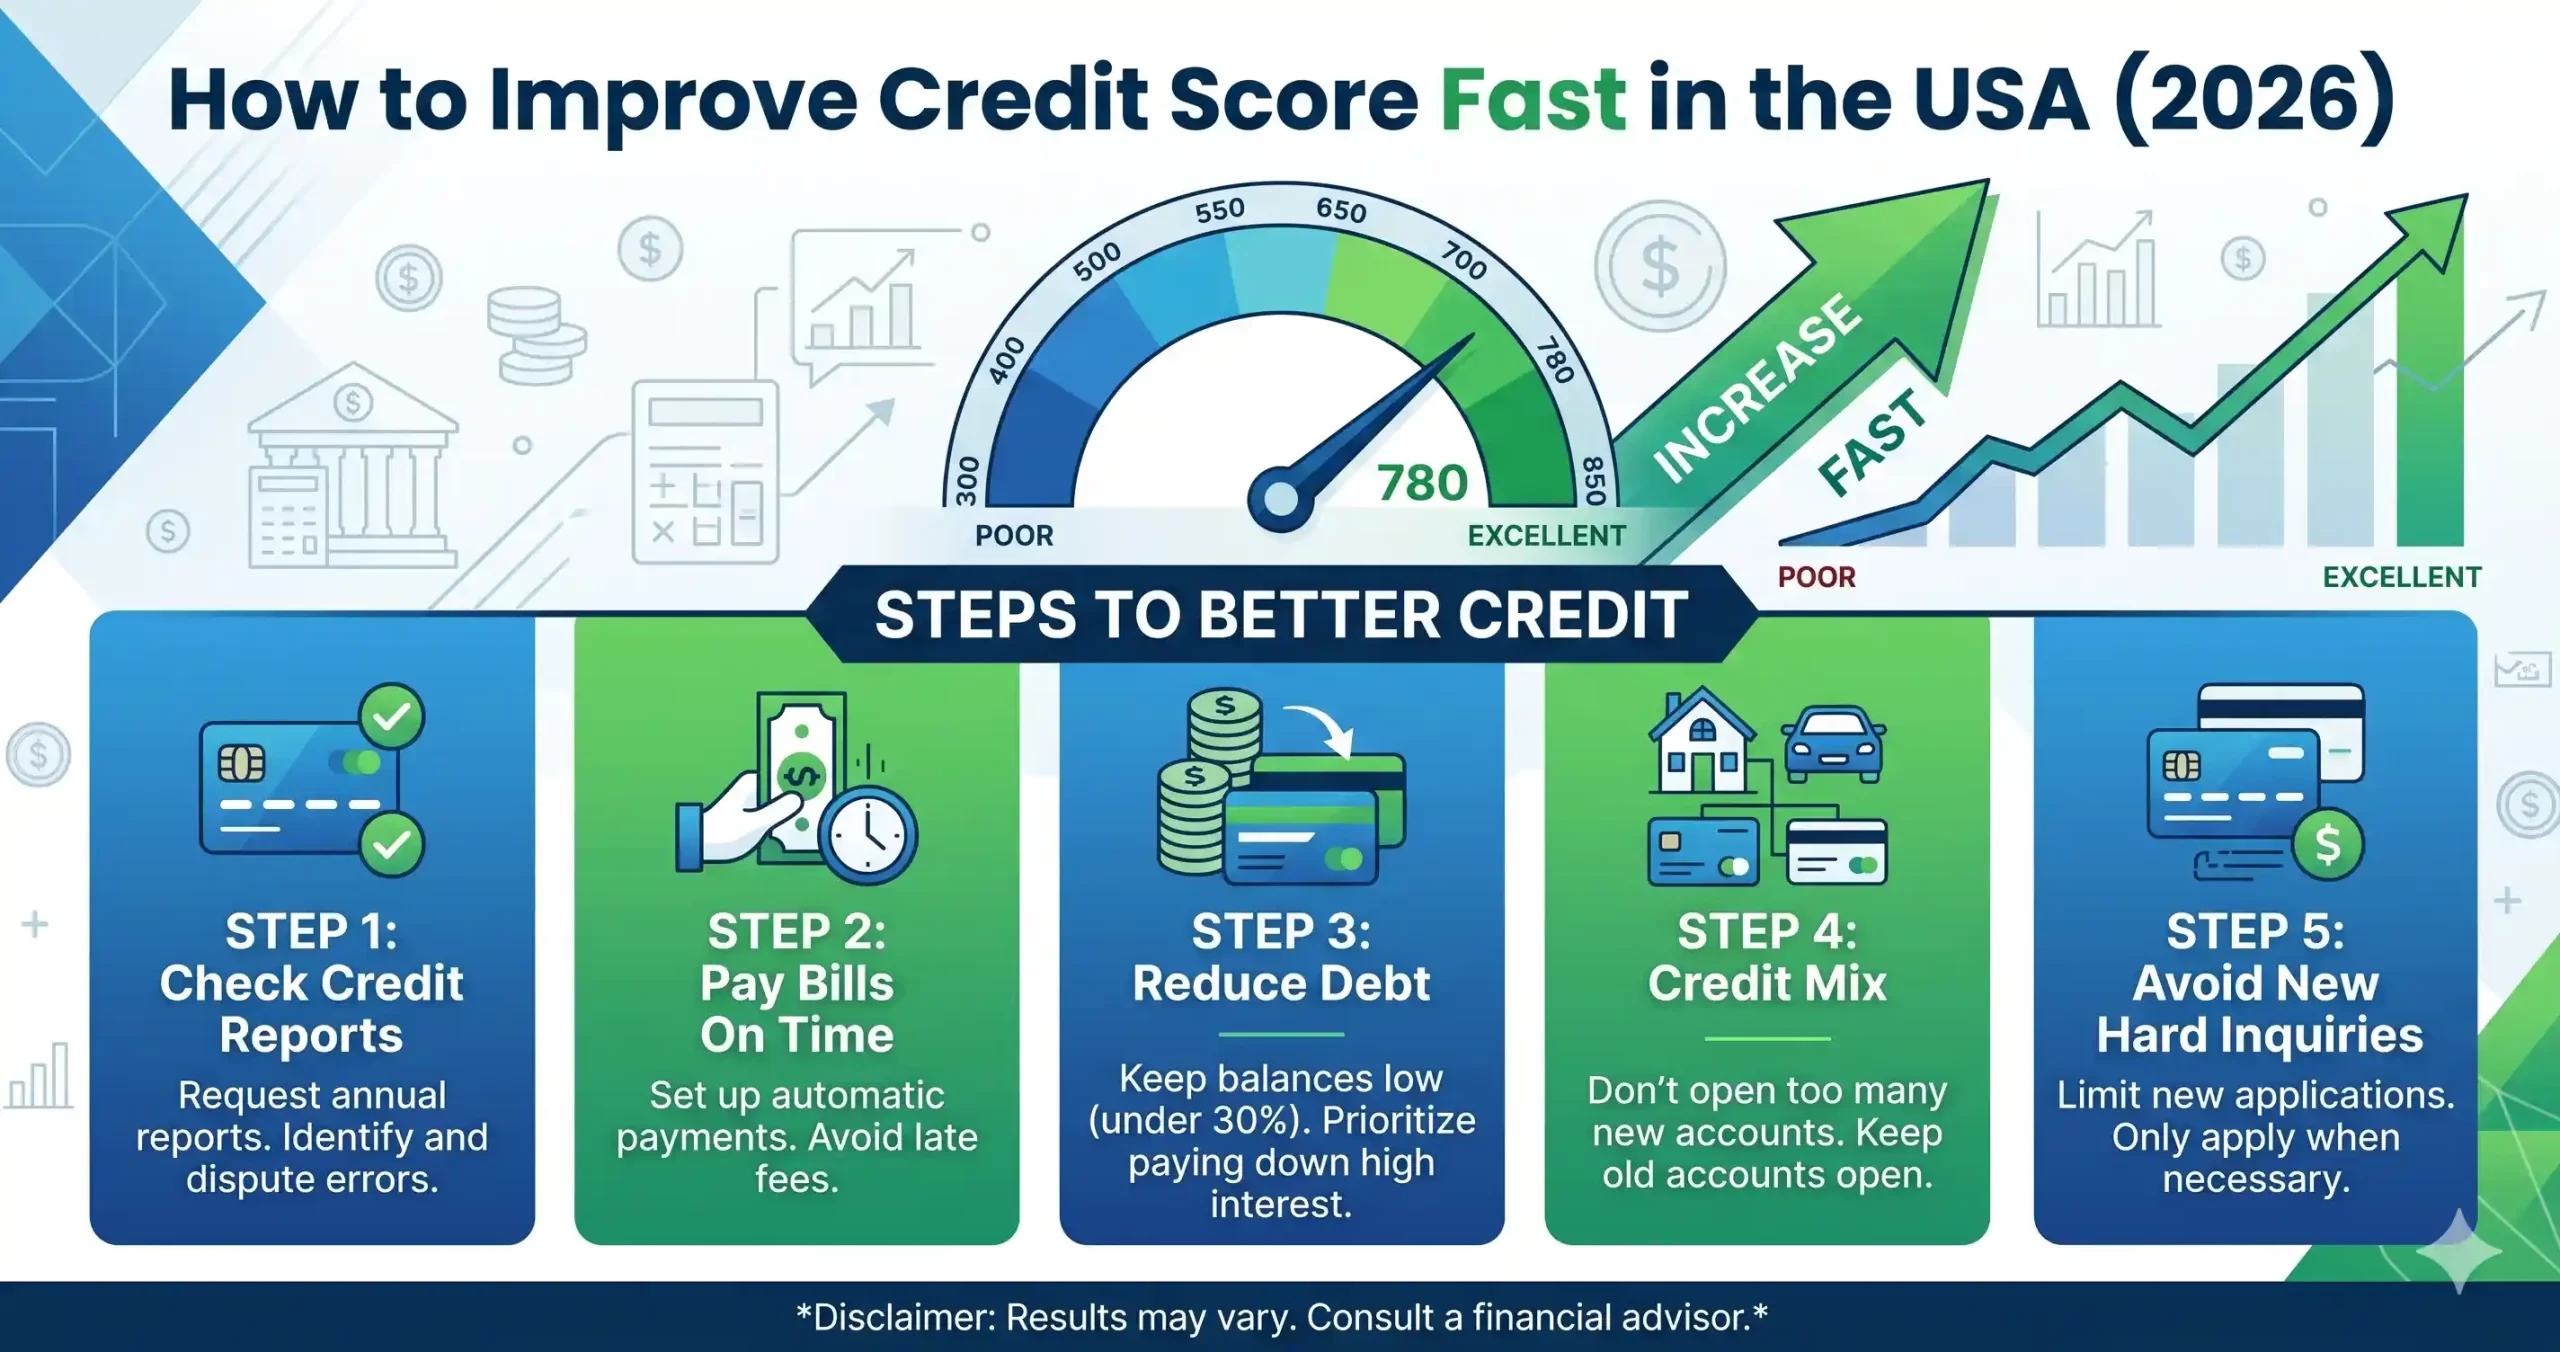
Methods that worked five years back are often inadequate today. In 2026, the most reliable method to develop credit is through a combination of micro-payments and diversified credit types. Rather of paying a costs once a month, many consumers now utilize automated systems to make weekly payments. This keeps the "typical everyday balance" low, which is a metric that 2026 algorithms weigh heavily. High utilization on the "declaration date" is no longer the only issue; the algorithms see the balance each and every single day.
- Cash-Flow Management: Keep a constant margin in between earnings and expenditures to please real-time monitoring tools.
- Energy Reporting: Opt-in to programs that report phone, web, and electrical power payments to the bureaus.
- Credit Mix: Guarantee a balance between revolving lines (cards) and installation loans (vehicle, personal, or credit-builder loans)
- Payment Frequency: Approach bi-weekly or weekly payments to reduce the effect of interest and lower typical balances.
In Delaware, credit-building specialized accounts have become a popular entry point for young experts. These accounts act as a hybrid between a cost savings account and a loan, where the transferred cash works as security. The 2026 version of these tools often includes a credit monitoring feature that provides instantaneous feedback on how the account is helping the user's profile. This instant satisfaction assists individuals remain motivated and constant with their financial objectives.
Regional Economic Consider Credit Scoring
Another shift in 2026 is the addition of local financial context. Algorithms now factor in the cost of living and the local job market in Delaware when determining risk. A $50,000 income in a high-cost location is viewed differently than the exact same earnings in a more budget friendly area. This hyper-local technique suggests that credit ratings are ending up being more relative. A "great" score in one part of the country may be computed utilizing somewhat various weights than a rating in another, depending upon the average debt levels and default rates of the local population.
Lenders are also looking at the stability of the employer and the market the consumer works in. In 2026, someone working in a high-growth sector in Delaware may receive slightly more beneficial terms due to the fact that the algorithm forecasts greater earnings stability. This has resulted in a more nuanced view of credit that represents the truth of the regional economy. While some critics argue this creates local variations, others explain that it enables more accurate lending in volatile markets.
Financial counseling has adjusted to this by providing localized recommendations. Rather of generic nationwide pointers, advisors in Delaware look at regional patterns to assist clients position themselves better for local loan providers. Comprehending how a local financial institution views danger in the current year is important for anybody seeking to protect a significant loan or mortgage.
Keeping Resilience in a Real-Time World
The speed of monetary information in 2026 methods that recovery from an obstacle can be quicker, however the margin for mistake is smaller sized. In the past, a missed payment might haunt a report for 7 years with extremely little a customer might do to offset it. Today, while the late payment remains, the "recovery period" is more visible. If a consumer reveals 6 months of impressive cash circulation and on-time payments following a mistake, the AI designs of 2026 are programmed to acknowledge the "rebound" and adjust the rating up quicker than older models did.
Remaining informed is the very best defense versus algorithmic volatility. The majority of people in Delaware now utilize apps that supply daily updates and informs for any changes in their profile. These tools typically recommend specific actions, such as "reallocate $200 from cost savings to pay for Card X," to optimize ball game for the following week. This level of granular control was non-existent in the past but is now a standard part of modern-day monetary life.
As we move through 2026, the relationship between the customer and the credit bureau is becoming more interactive. It is no longer a one-way street where the bureau dictates an individual's worth. Through using modern digital tools, individuals have the power to share more of their monetary story, showing their dependability through a broader variety of data. The objective of these modern algorithms is not to omit people, however to find more ways to say "yes" by looking at the entire photo of a person's monetary life.

Latest Posts
Finding No-Cost Credit Assistance for Me in 2026
Building Credit Through Advanced Financial Literacy Education
A Guide to Improving Credit in 2026