All Categories
Featured
Table of Contents
Shifting Truths of Credit Evaluation in Texas
The monetary environment of 2026 has moved away from the static, month-to-month snapshots that specified the previous decade. For homeowners in Texas, the way creditworthiness is measured now counts on a continuous stream of information points instead of a single number upgraded every thirty days. Modern algorithms have actually approached cash-flow underwriting, which focuses on actual liquidity and costs routines over historical debt management alone. This change suggests that a person's everyday financial habits brings more weight than it did just a couple of years back.

Financial therapists in 2026 stress that the traditional credit report is becoming a secondary metric. Lenders are increasingly utilizing proprietary models that incorporate straight with bank accounts to confirm income and outbound costs in real-time. This shift has actually been driven by the requirement for more precise danger evaluation in an economy where gig work and non-traditional income streams are common. For those residing in Texas, these modifications offer both chances and challenges, as a single month of poor money management can assess a profile much faster than under older systems.
One noteworthy development in 2026 is the extensive adoption of trended data. Instead of taking a look at a balance on a particular day, algorithms now examine whether a customer is "paying down" or "revolving" their debt over a 24-month period. This distinction assists lenders determine individuals who are caught in a cycle of debt versus those who are actively improving their financial position. Many individuals find that concentrating on Security Clearance Protection helps keep a positive trajectory even if their overall debt stays moderate.
Combination of Option Data Points
By 2026, the inclusion of "alternative" information has ended up being standard practice across all significant bureaus. This includes lease payments, energy costs, and even membership services. Formerly, these products only appeared on a report if they went to collections, however contemporary models reward consistent on-time payments for these daily expenditures. This change has actually helped millions of people with "thin" credit files establish a footprint without requiring to take on high-interest charge card debt.
In Texas, local residential or commercial property management firms and energy providers have actually largely automated the reporting of these payments. Counselors typically encourage clients to guarantee their Credit Counseling is properly connected to these accounts to take full advantage of the benefit. If a person pays lease on the very first of the month for 3 years directly, the 2026 algorithms treat this as a high-intent indicator of reliability, similar to a mortgage payment. This leveling of the field enables renters to complete for much better rates of interest on auto loans and credit lines.
Expert techniques now involve "data health" rather than simply balance management. Customers are motivated to audit their digital financial footprint to ensure that no small, forgotten subscriptions are causing friction in their data stream. Due to the fact that Effective Debt Prioritization Strategies supplies a clear window into monetary habits, keeping a tidy and predictable costs pattern is the most effective way to develop a high score in the current year.
The Impact of AI and Predictive Modeling

Artificial intelligence has fundamentally changed how danger is computed in 2026. Unlike older direct models, AI-driven algorithms can identify complex correlations that humans may miss. An unexpected shift in where a person stores or a change in the frequency of small-dollar transfers can set off a threat alert. These designs are not trying to find a specific mistake, however rather a change in the "monetary speed" of the person. This predictive nature implies that ratings can fluctuate based on viewed future danger, even if no payments have actually been missed out on.
This predictive modeling has actually caused the rise of personalized credit training. Therapists in Texas use software application that mirrors these AI designs to offer customers a "pre-score" evaluation. This permits people to see how a specific purchase or a brand-new credit query may impact them before they act. In 2026, the objective is to get rid of the mystery of why a score relocations. Most customers now have access to "what-if" simulators that are even more accurate than the generic tools available in the early 2020s.
For those looking to improve their standing, the focus has actually moved towards "positive signaling." This includes purposefully producing information points that the AI views as low-risk. Many individuals looking for Credit Counseling for Abuse Survivors discover that keeping a high "buffer" in their checking account is simply as essential as keeping credit card balances low. The algorithm views a consistent money reserve as a sign that the consumer is not likely to rely on high-interest debt throughout an emergency.
New Credit Structure Techniques for 2026
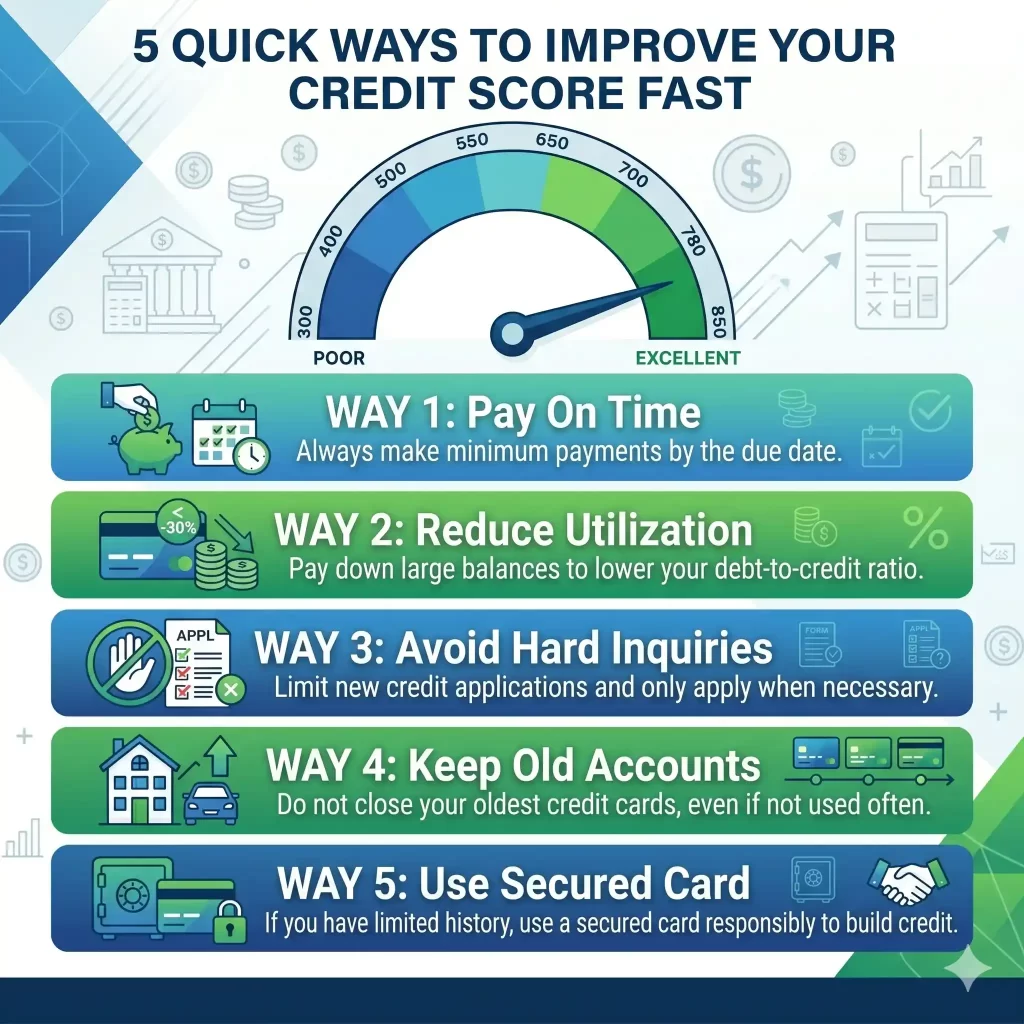
Techniques that worked 5 years earlier are frequently inadequate today. In 2026, the most reliable way to build credit is through a mix of micro-payments and diversified credit types. Instead of paying a costs when a month, numerous customers now use automated systems to make weekly payments. This keeps the "average daily balance" low, which is a metric that 2026 algorithms weigh heavily. High usage on the "statement date" is no longer the only issue; the algorithms see the balance each and every single day.
- Cash-Flow Management: Keep a consistent margin in between earnings and costs to satisfy real-time monitoring tools.
- Energy Reporting: Opt-in to programs that report phone, web, and electrical energy payments to the bureaus.
- Credit Mix: Ensure a balance in between revolving lines (cards) and installment loans (auto, individual, or credit-builder loans)
- Payment Frequency: Move towards bi-weekly or weekly payments to reduce the effect of interest and lower typical balances.
In Texas, credit-building specialized accounts have actually ended up being a popular entry point for young professionals. These accounts act as a hybrid in between a savings account and a loan, where the transferred cash serves as security. The 2026 variation of these tools often includes a Credit Counseling that offers instantaneous feedback on how the account is helping the user's profile. This instant satisfaction helps people stay inspired and consistent with their financial goals.
Regional Economic Consider Credit Scoring
Another shift in 2026 is the inclusion of regional economic context. Algorithms now aspect in the cost of living and the regional job market in Texas when identifying danger. A $50,000 income in a high-cost area is viewed in a different way than the same earnings in a more cost effective region. This hyper-local technique implies that credit history are ending up being more relative. A "good" rating in one part of the country might be determined utilizing slightly various weights than a score in another, depending on the typical debt levels and default rates of the local population.
Lenders are likewise taking a look at the stability of the employer and the market the customer operates in. In 2026, someone working in a high-growth sector in Texas might get slightly more favorable terms because the algorithm anticipates higher income stability. This has actually caused a more nuanced view of credit that accounts for the truth of the local economy. While some critics argue this produces local disparities, others point out that it enables more precise loaning in unpredictable markets.
Monetary counseling has adjusted to this by offering localized recommendations. Rather of generic nationwide ideas, consultants in Texas take a look at local patterns to help clients position themselves much better for local lenders. Comprehending how Credit Counseling views risk in the present year is vital for anybody looking to secure a significant loan or home loan.
Maintaining Durability in a Real-Time World
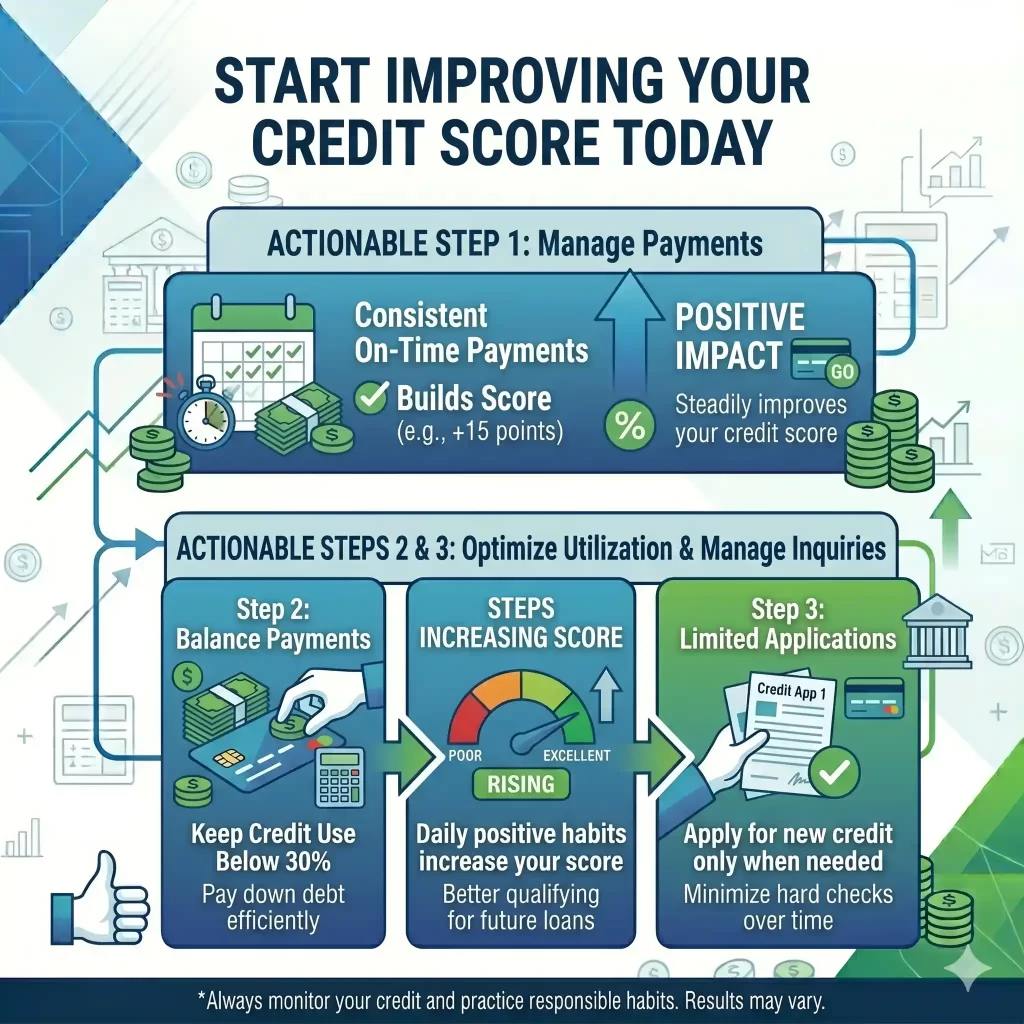
The speed of monetary data in 2026 ways that recovery from a problem can be faster, however the margin for mistake is smaller. In the past, a missed out on payment could haunt a report for seven years with very little a customer might do to offset it. Today, while the late payment stays, the "recovery duration" is more visible. If a consumer shows 6 months of remarkable money circulation and on-time payments following a mistake, the AI models of 2026 are programmed to acknowledge the "rebound" and adjust ball game up faster than older designs did.
Remaining notified is the finest defense against algorithmic volatility. A lot of people in Texas now use apps that provide day-to-day updates and informs for any changes in their profile. These tools often suggest particular actions, such as "reallocate $200 from cost savings to pay for Card X," to optimize ball game for the following week. This level of granular control was non-existent in the past but is now a basic part of contemporary financial life.
As we move through 2026, the relationship in between the customer and the credit bureau is ending up being more interactive. It is no longer a one-way street where the bureau determines a person's worth. Through the use of Credit Counseling, individuals have the power to share more of their monetary story, showing their reliability through a larger variety of information. The objective of these modern algorithms is not to omit people, however to discover more methods to state "yes" by looking at the entire image of an individual's financial life.

Latest Posts
Finding No-Cost Credit Assistance for Me in 2026
Building Credit Through Advanced Financial Literacy Education
A Guide to Improving Credit in 2026